MTD from April 2027: A Checklist for the £30,000 Group
If your 2025-26 self-employment and property income is over £30,000, Making Tax Digital starts for you on 6 April 2027. Here's how to check, what to do before then, and your first deadlines.
The short answer
If your qualifying income (self-employment plus property income before expenses) on your 2025-26 tax return is over £30,000, you must use Making Tax Digital for Income Tax from 6 April 2027. HMRC estimates around 1,077,000 more sole traders and landlords are affected. Your first quarterly update, covering 6 April to 5 July 2027, is due 7 August 2027.
On 5 October 2026 HMRC started urging the next group to get ready: sole traders and landlords whose income is over £30,000. From 6 April 2027 around 1,077,000 more people join Making Tax Digital for Income Tax, by HMRC's estimate.
If that might be you, here's a checklist.
Are you in?
You need MTD from 6 April 2027 if all of these apply:
- you're a sole trader or landlord registered for Self Assessment;
- your qualifying income for 2025-26 is over £30,000;
- you're not exempt.
Qualifying income is your self-employment and property income before expenses (turnover), added together. A £20,000 rental and a £12,000 side business make £32,000, so you're in, even if your profit is far lower. Wages, pensions, dividends and a partnership profit share don't count. Full rules in what counts as qualifying income.
The figure comes from your 2025-26 tax return, due by 31 January 2027. File it early and you'll know for sure.
The threshold falls again to £20,000 from April 2028, based on 2026-27 income. If you're just under £30,000, you may only have a year's grace.
The checklist
Before 31 January 2027
- File your 2025-26 return the usual way. It decides whether you're in, and you still have to file it whatever happens with MTD.
- Work out your qualifying income from that return.
- Check for exemptions. For example, people who are digitally excluded, or who are covered by temporary exemptions ending in April 2027. See MTD exemptions.
Before 6 April 2027
- Choose compatible software that covers all your income sources.
- Sign up (or let HMRC sign you up). To sign up you must be registered for Self Assessment and have filed a return in the last two years. Your accountant can do it for you. See how to sign up.
- Authorise your software with HMRC and check the accounting period it's set to. If your accounts run 1 April to 31 March, select calendar update periods before your first update.
- Separate business and personal money if you haven't already. It makes digital records far easier.
From 6 April 2027
- Keep digital records of every business and property transaction from the first day of the tax year.
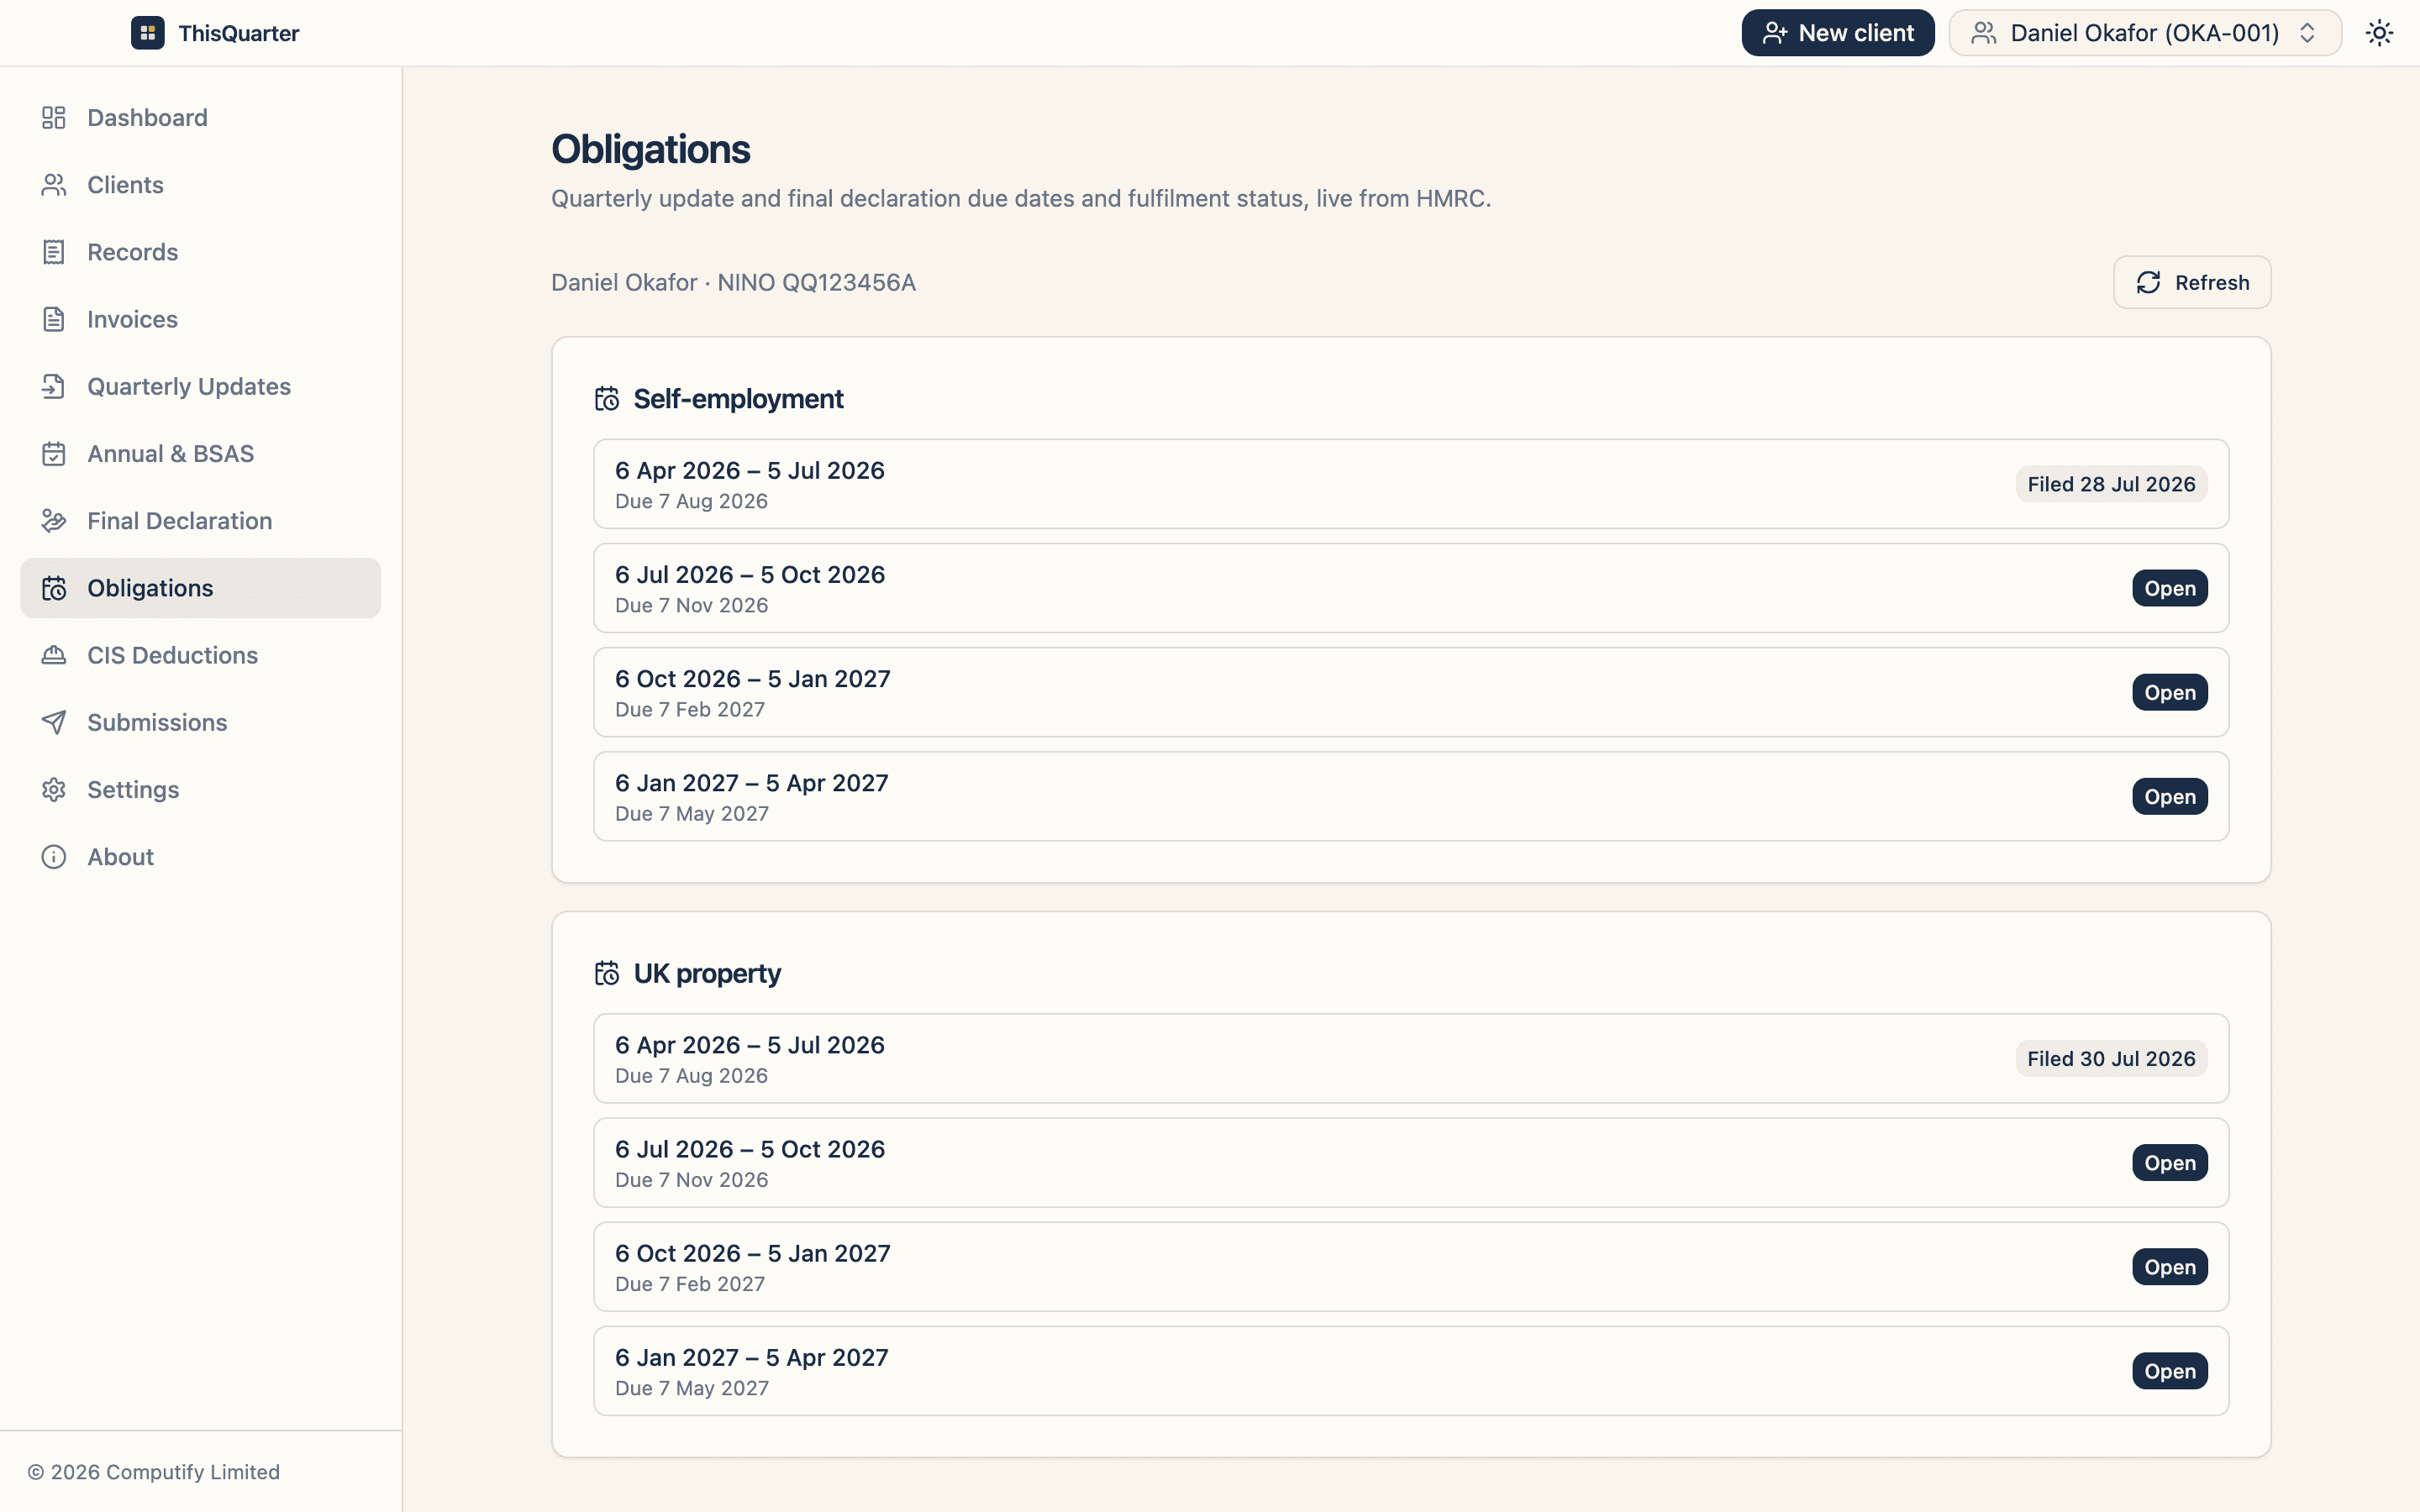
- Send quarterly updates by 7 August, 7 November, 7 February and 7 May.
Your first-year deadlines
| What | Period | Deadline |
|---|---|---|
| Quarterly update 1 | 6 Apr – 5 Jul 2027 | 7 Aug 2027 |
| Quarterly update 2 | 6 Apr – 5 Oct 2027 | 7 Nov 2027 |
| Quarterly update 3 | 6 Apr – 5 Jan 2028 | 7 Feb 2028 |
| Quarterly update 4 | 6 Apr 2027 – 5 Apr 2028 | 7 May 2028 |
| Tax return (2027-28) | Whole year | 31 Jan 2029 |
Each update is cumulative, covering the whole year so far. A correction just flows into the next one.
Penalties: no soft landing this time
The 2026-27 group had no penalty points for late quarterly updates in their first year. That easement was for 2026-27 only. Under the points system a late update earns a point, and four points mean a £200 penalty. See MTD penalties explained.
Leave room for the first update
The first update is mostly setup work: getting categories right, linking accounts and checking opening figures. Doing a dry run with April and May's figures leaves plenty of time before 7 August.
How ThisQuarter helps. ThisQuarter reads your obligations from HMRC, takes manual entry or a spreadsheet import, and shows every figure and where it came from before you send. If you're an accountant onboarding the £30k group, client authorisations run from inside the app. See how it works.
Sources
- Sole traders and landlords earning more than £30,000 urged to act now (HMRC press release, 5 October 2026)
- Find out if and when you need to use MTD for Income Tax (GOV.UK)
- Send quarterly updates (GOV.UK)
Frequently asked questions
Is the £30,000 based on turnover or profit?
Turnover. Qualifying income is your gross self-employment and property income before expenses or allowances, so a business with £35,000 of sales and £20,000 of costs is still in.
Which tax year decides whether I'm in from April 2027?
Your 2025-26 tax year, as reported on the 2025-26 return due by 31 January 2027.
When is my first MTD deadline?
Your first quarterly update covers 6 April to 5 July 2027 and is due by 7 August 2027. Your first MTD tax return, for 2027-28, is due by 31 January 2029.
Will HMRC tell me?
HMRC writes to people it identifies from their return, but GOV.UK is clear that it's still your responsibility to check if you don't get a letter.
Related reading
Starting a New Business or Rental Under MTD: When Do Updates Begin?
Already in Making Tax Digital and starting a new business or letting? Quarterly updates for the new source usually don't start straight away. Here's when they do, how to add it, and when a new property isn't a new source at all.
HMRC Signed Me Up for Making Tax Digital: What to Do Now
Got a letter saying HMRC has signed you up for MTD for Income Tax? Here's why it happened, the five steps to take, how to catch up on missed quarterly updates, and what to do if you think it's wrong.
How to Sign Up for MTD for Income Tax: Step by Step
A step-by-step guide to signing up for Making Tax Digital for Income Tax — what you need, how to register with HMRC (or through your software or accountant), and what happens after you join.